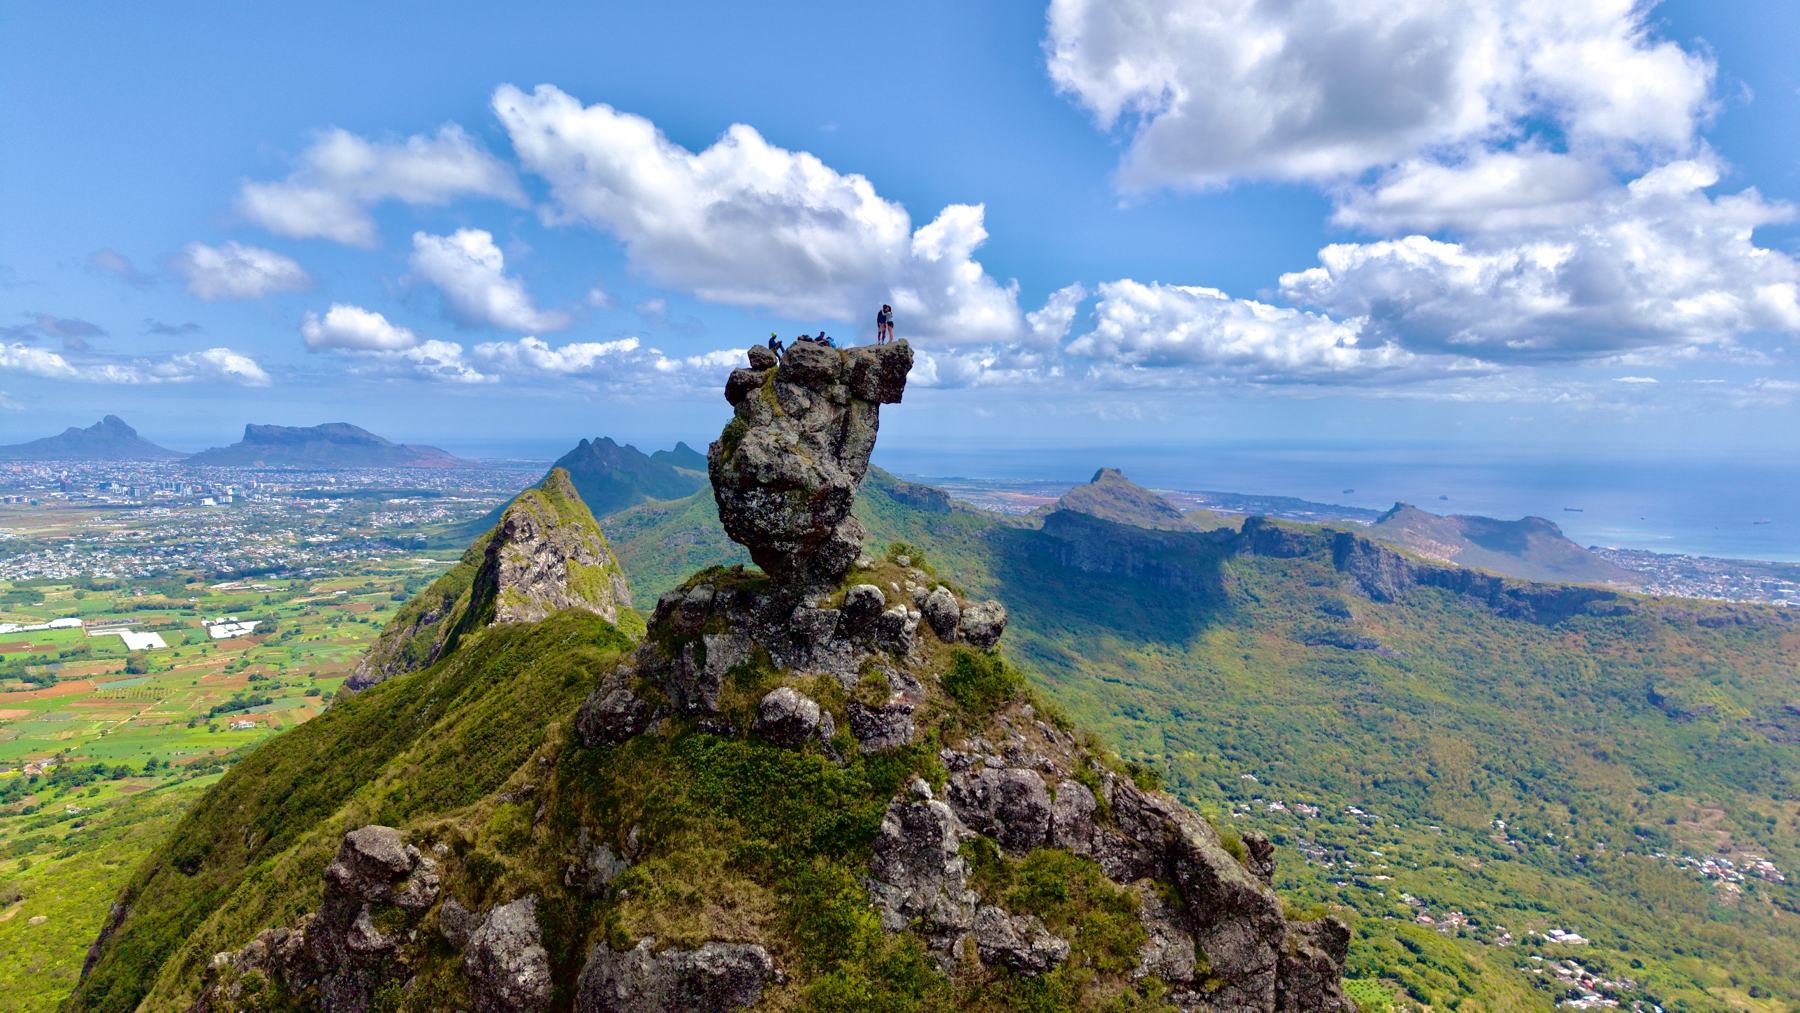
Connecting capital to trade across Africa, Asia and Mauritius.
A boutique consulting firm led by a former senior banker. We help businesses prepare and structure transactions, then introduce them to the banks, guarantors and licensed partners who can say yes.
3 decadesCorporate, international and central banking
3 regionsAfrica, Asia and Europe
FSAOfficial business introducer, African Solidarity Fund
MauritiusOur hub for FSC-compliant structures
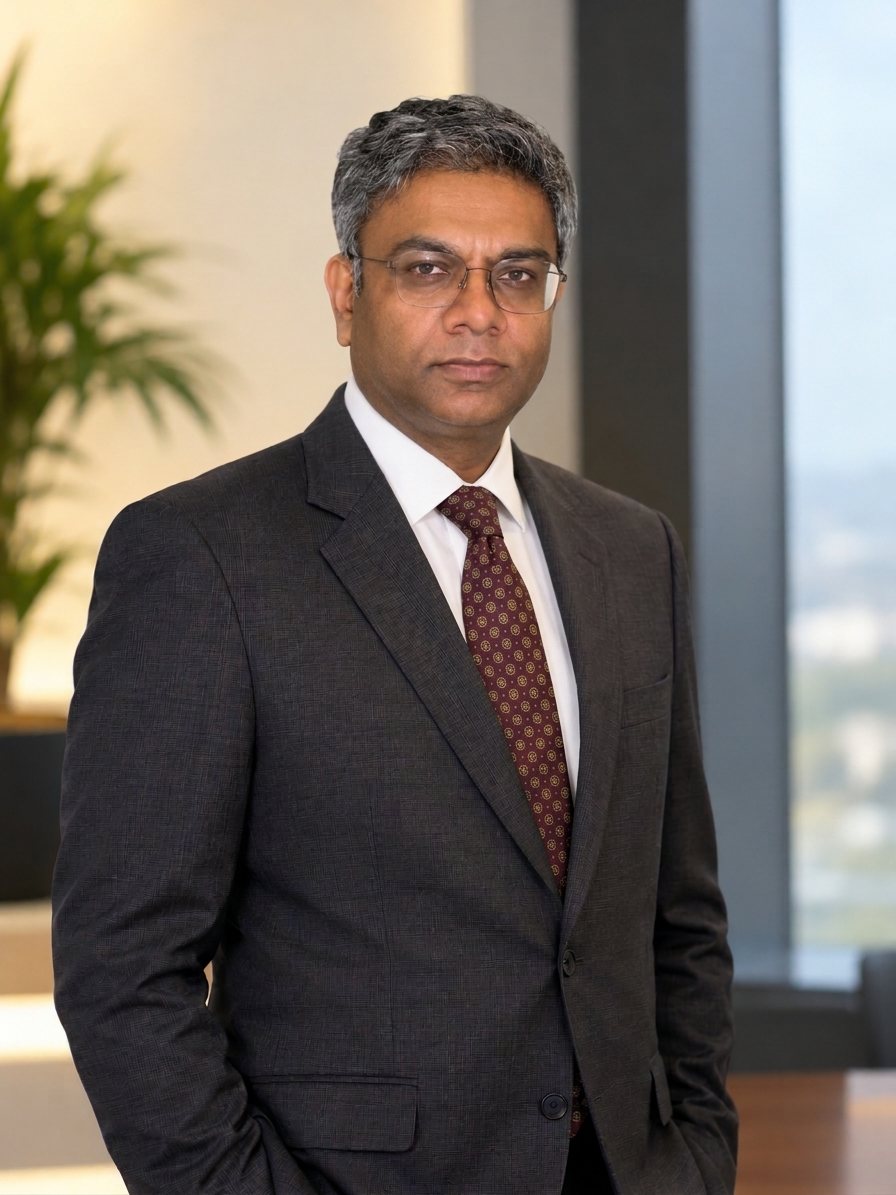
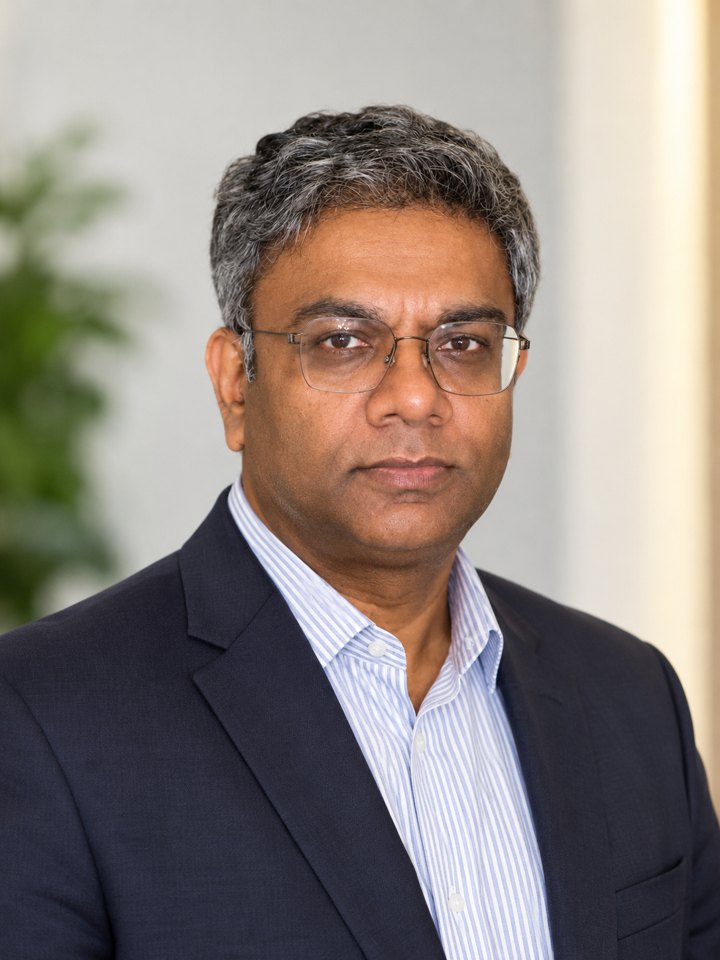
A word from our founder
Trade runs on trust, and trust is built across a table.
After three decades in corporate and international banking and central banking, I started Nakhoda to work with businesses directly: helping them reach the banks, guarantors and structures that fit, across Africa, Asia and beyond.
We are a small firm by design, so the person you meet is the person doing the work.
We support and structure tailored financial solutions for cross-border businesses across Asia, Mauritius and Africa, connecting clients with appropriate financial institutions and solution providers.
Helping businesses reach the capital, banks and structures they need.
Trade and capital
Trade finance, FSA guarantees and financing, helping credible transactions reach the banks, guarantors and lenders who can say yes.
Banking, payments and structures
Account opening, faster payment settlement and Mauritius structuring, with licensed professionals carrying out the regulated work.
Property and practical support
Introductions to trusted real estate agents, and help with residency permits for clients setting up in Mauritius.
Commodities and trade finance.
Securing your international operations.
Africa's trade finance gap
A large, persistent shortfall, and the reason good deals stall.
US$74–92bnUnmet trade finance demand in Africa in 2024, about 5.4% of the continent's merchandise trade.
23%Share of Africa's trade supported by commercial banks in 2020–24, down from 40% before the pandemic and about 80% globally.
37%Of trade finance applications were rejected by banks in 2020–24. SMEs are hit hardest, with a 63% approval rate.
US$87–103bnPossible gap by 2027 in a moderate-to-severe scenario, at least 17.7% above 2024 levels.
Why applications fail. Banks most often cite weak creditworthiness (48% of banks) and insufficient collateral (39%). The global gap is estimated at about US$2.5 trillion.
Where we fit. This is the gap we work in: helping credible transactions reach the banks and guarantors that can say yes. We assist and introduce; financing is provided by third parties.
Sources: African Development Bank, Trade Finance Supply in Africa: Post-Covid Trends and Emerging Opportunities (2026), as reported by Global Trade Review and BusinessDay (May 2026); Asian Development Bank, Global Trade Finance Gap Survey (2025). Estimates; check against the original reports before relying on them.
Overview
We help exporters, importers, traders and intermediaries structure and execute secure trade finance transactions across borders.
We work directly with buyers and sellers to:
Assess deal viability
Structure the right financial instruments
Keep transactions moving smoothly, from early discussions through to issuance, documentation and completion
Liquidity solutions for banks
We help banks access liquidity through structured LC prepayment, bringing forward the proceeds of letters of credit ahead of their maturity.
Prepayment of letter of credit proceeds
Structured around the bank's liquidity needs
Subject to due diligence and the requirements of the parties involved
Instruments and services
Instruments
LCLetters of Credit
SBLCStandby Letters of Credit
BGBank guarantees
We also source guarantors for
Bid bonds
Performance bonds
Advance payment guarantees
How we help
01
Trade documentation
Clarity and process guidance on trade documentation.
02
Coordination
Coordination with banks, financial institutions and counterparties.
03
Deal execution
End-to-end deal execution and long-term client relationships.
04
Cross-border support
We support trade flows across multiple jurisdictions, with a strong emphasis on transparency, structure and reliability.
Structured trade and commodity finance
We also focus on structured trade and commodity finance throughout Africa, and on providing structured trade finance solutions for Africa and the Middle East.
AfricaMiddle East
India–Africa trade
Trade facilitation and strategic sourcing.
Connecting credible Indian and African suppliers and buyers.
We facilitate trade and commercial partnerships between India and Africa by connecting credible suppliers, manufacturers, producers and buyers across markets.
Operating through a cross-border facilitation model, we help businesses identify suitable products, access reliable counterparties and explore mutually beneficial commercial opportunities. We act as a conduit between the two regions, bringing together market knowledge, business networks and transaction coordination to help turn sourcing opportunities into viable commercial relationships.
Suppliers, manufacturers, producers↔Nakhoda↔Buyers across Africa
We assist and introduce. We do not issue instruments or lend, and any financing is provided by third parties on their own terms.
We are the official business introducer for the African Solidarity Fund (FSA), a multilateral financial institution that guarantees financing for investment projects across its African member states.
Official business introducer · African Solidarity Fund (FSA)
About the FSA
Founded in 1975 and a specialised agency of the African Union since 2025, the FSA is headquartered in Niamey, Niger, with a resident mission in Mauritius.
23African member states, including Mauritius
Baa1Moody's rating, stable outlook
AAA+GCR Ratings, positive outlook
Ratings as reported by the FSA.
What it offers
Guarantees that share risk with lenders and bond subscribers, so that sound projects can raise financing. Available for businesses in member states, across sectors such as infrastructure, mining, agro-industry, transport and financial services.
Fit checkWe check that the business plan submitted by the borrower is in line with the FSA's requirements.
Prepare the fileWe help the borrower assemble the application and supporting documents.
IntroduceWe present the completed file to the FSA.
FSA decisionThe FSA appraises and decides, on its own terms.
We introduce and prepare. We do not issue guarantees or speak for the FSA, and an introduction does not guarantee approval. Fees, limits and eligibility are set by the FSA, and we can share them on request.
We introduce projects, corporates and financial institutions to banks, DFIs and private credit providers, and help you organise the documents a lender expects to see.
What we help with
Sovereign, bank, corporate & project financing
Introductions to financiers across all four borrower types.
Capital connections
Introductions to providers whose appetite fits. We do not advise on which financing to choose.
Document organisation
We help you gather and organise the information and documents lenders ask for. Financial models, term sheets and credit applications are prepared by you or your licensed advisers.
How we support you
01
Process guidance
Walking you through what banks, DFIs and private credit providers ask for, and in what order.
02
Proposals and financing requests
Helping you review your business proposal and your financing request to the bank, based on your own information and figures.
03
Information readiness
Helping you bring your business information and supporting documents together, complete and consistent.
04
Lender introductions
Introductions to financiers whose appetite and geography fit your profile, in English and French.
05
Engagement coordination
Managing information requests, timelines and counterparties, alongside your own licensed advisers, through to completion.
Who we engageDFIsBanksPrivate creditFinancial institutionsGlobal commodity entities
Where we sit in a transaction
We do
Help you organise your documents
Introduce you to financiers
Coordinate documents and communication between parties
Consult on business strategy and market entry
Licensed partners do
Lend, underwrite and issue guarantees
Give corporate finance advice and prepare financial models, term sheets and credit applications
Manage companies, trusts and funds
Give regulated investment, legal and tax advice
You decide
Whether to proceed with an introduction
Which terms to accept
Which professionals to appoint
Financing is provided by third-party financiers on their own terms. We do not lend, commit funds or give corporate finance advice.
Bank account opening and on-boarding.
We help foreign individuals and corporates through the compliance and on-boarding steps of opening accounts.
Bank account opening
Facilitating bank account opening for foreign individuals and corporates.
On-boarding documentation
Guidance through compliance and on-boarding documentation for corporate and private accounts.
Regulatory alignment
Aligning client goals with the FSC and EDB regulatory frameworks.
Each bank decides on account opening after its own checks.
Mauritius structuring, treaty routing and compliance.
Mauritius as an international financial centre hub for holding and financing vehicles, with the compliance framework that cross-border transactions need.
Illustrative routing
Europe · AsiaInvestor, cross-border investment
→
Mauritius GBCHolding or financing vehicle
→
AfricaTarget market
Illustration only. Tax outcomes depend on the treaty in force, the structure's substance and your own tax advice.
Management Company introductions
Introductions to licensed Management Companies in Mauritius for GBCs, Authorised Companies, Trusts, Foundations and other special licences issued by the FSC. We then liaise between the Management Company and the bank on account opening, and help resolve any missing information or documentation queries along the way.
GBC structuring
Global Business Company structuring for cross-border investment.
DTAA routing
DTAA-based, tax-efficient routing from Europe and Asia to Africa.
Holding & financing vehicles
Mauritius as an IFC hub for holding and financing vehicles.
AML / KYC frameworks
Compliance frameworks for cross-border transactions.
Licensed Management Companies carry out regulated work, including company administration. We introduce and coordinate.
Faster, lower-cost payments between Africa and China.
We help African companies settle payment obligations to Chinese exporters more quickly and at lower cost, through cross-border trade optimisation strategies.
The idea
Fewer intermediary banks, fewer currency conversions, and a settlement route that suits the corridor.
Typical route
Local currency→USD→CNY
Two conversions and several intermediary banks, each adding cost and delay.
Optimised route
Local currency→CNY
One conversion over a bilateral local currency rail, with fewer intermediaries.
How we help
01
Local currency settlement and alternative clearing
We help clients avoid the double conversion trap, local currency to USD to CNY, by using bilateral local currency payment rails.
We guide clients in using the various payment platforms to clear intra-African trade, or to connect directly with emerging Asian clearing mechanisms.
We guide clients in using CNY-denominated trade accounts to reduce reliance on Western intermediary banks, lowering wire fees.
02
Alternative B2B fintech and digital payment rails
We help clients move away from slow legacy channels to modern digital payment service providers that specialise in emerging markets.
We introduce clients to licensed payment service providers and payment intermediary services built for emerging market corridors.
What it can mean for youFaster settlementLower transfer costsFewer currency conversionsRegional clearing access
We guide and introduce. Payments are processed by licensed banks and payment providers. Savings and speed depend on the corridor, the currencies and the providers involved.
Practical support for settling and doing business in Mauritius.
Administrative assistance, guidance and coordination alongside our core work. More services will be added here.
Four services. Select one to read the detail.
01
Residency permit facilitation
Settle in Mauritius with confidence.
Guided support through the residency application process.
We accompany foreign nationals through the administrative procedures involved in obtaining residency in Mauritius.
Our services cover
Residency pathway guidance
EDB application assistance and administrative formalities
Medical examinations and laboratory test coordination
Document collection, preparation and verification
Appointment scheduling and administrative follow-up
Assistance with dependent and family applications, where applicable
Personalised accompaniment throughout the application process
Our services consist of administrative assistance, guidance and coordination. Permit eligibility, requirements and approval remain subject to the applicable laws and decisions of the competent Mauritian authorities. Medical services are provided by qualified healthcare professionals.
02
Africa–India workforce solutions
Connecting businesses with international talent.
Introductions to Indian workforce-service providers for Mauritian businesses.
We facilitate cross-border business collaboration between Mauritian enterprises and established Indian workforce-service providers. Through our strategic partnership in India, we help businesses explore workforce solutions aligned with their operational requirements, industry needs and growth objectives.
Our services include
Workforce requirements assessment and business needs coordination
Strategic introductions to our Indian workforce-service partner
Facilitation of employer–partner engagement
Coordination of talent-sourcing requirements and service delivery
Support in exploring workforce solutions across technology, engineering, finance, healthcare, hospitality, manufacturing and other selected sectors
Our role is focused on business development, partnership facilitation and coordination, working alongside our Indian partner and appropriately authorised service providers and recruitment agencies.
03
Health care
Market entry and international business development.
Business development and market entry for health care manufacturers and distributors.
We support international businesses seeking to establish and develop their presence in Mauritius and selected African markets. Working alongside overseas manufacturers and strategic partners, we provide business development, market-entry support and commercial coordination designed to open access to new markets and distribution opportunities.
Our services include
Market-entry strategy and commercial opportunity assessment
Business introductions and strategic representation
Identification of potential distributors, wholesalers and retail partners
Commercial partnership development and negotiation support
Coordination of import, distribution and product-launch workstreams
Liaison with relevant professional advisers and regulatory specialists
Development of commercial relationships between Indian manufacturers and African businesses
Our approach is partnership-driven, combining local market knowledge, business networks and international commercial relationships to help clients explore and develop new opportunities.
04
SME debt management
Financing support for small and medium businesses.
Helping SME owners understand their debt and prepare for lender discussions.
We help business owners understand their existing financial commitments, assess what their business can realistically sustain, and prepare more effectively for conversations with lenders.
Debt and loan management
Loan restructuring, refinancing reviews and repayment management.
Financial health and cash-flow review
A clear view of debt capacity and working capital, so owners know what the business can sustain.
Banking and financing preparation
Support with financial documentation and financing proposals, and preparation for lender discussions.
Our role is consulting and preparation. Lending decisions rest with banks and lenders, and regulated advice is provided by licensed professionals.
Real estate, through trusted introductions.
When a client needs property support, we connect them with our trusted real estate agents.
Overview
Property is not our main business, but our clients sometimes need it. Where that is the case, we introduce them to agents we trust and stay close to the process.
How we help
Introductions to our trusted real estate agents for acquisitions and other property transactions
Residential, commercial, industrial, hospitality and land property
Introductions for foreign buyers looking at property in Mauritius
We are not a registered real estate agent under the Real Estate Agent Authority Act 2020. Our trusted agents handle the transactions, and we do not advise on them.
A trusted, treaty-backed gateway for investment, structured finance and trade across India, Africa and the Middle East.
The case in brief
Mauritius has grown from a small island economy into one of the most established international financial centres between Asia and Africa. Investors choose it for a stable democracy, a hybrid common and civil law system, a bilingual workforce, no exchange control and a regulator that has proved it can meet international standards.
Stable and openDemocratic, English and French, no exchange control.
Law you can rely onHybrid common and civil law, with Privy Council appeal.
Internationally testedA regulator that has met FATF and EU standards.
12,900+Global Business licences, 2023
~1,000Funds operating from the jurisdiction
USD 750 bn+Assets held by Global Business Companies, 2023
50thGlobal Financial Centres Index, March 2026 (up from 58th)
A regulatory record that has been tested and restored
21 Oct 2021
FATF removes Mauritius from its grey list, after listing in February 2020.
7 Jan 2022
European Commission removes Mauritius from its high-risk third country list.
Mar 2026
Global Financial Centres Index places Mauritius 50th, up eight places in a year.
2027
Next FATF / ESAAMLG mutual evaluation, which is shaping current regulatory priorities.
Two clear regulators
The Bank of Mauritius supervises the banking sector. The Financial Services Commission is the integrated regulator for non-bank financial services and global business, and is digitalising its licensing and strengthening AML/CFT supervision under Budget 2026/27.
A dependable legal system
A Westminster-style constitution built on the rule of law and separation of powers. Mauritian law blends common law and civil law, and the country hosts an international arbitration centre.
3%Effective rate on specified income, where substance requirements are met
An 80% partial exemption applies to specified income such as foreign dividends and interest. The regime was retained in Budget 2026/27.
0%
Capital gains tax
No tax on capital gains.
None
Exchange control
Free repatriation of profits.
40+
Tax treaties
Double taxation agreements, plus foreign tax credits where taxes paid abroad can be evidenced, and around 30 investment promotion and protection agreements in force.
Global minimum tax
In-scope multinational groups face the global minimum tax framework, including a domestic top-up tax that started on 1 July 2025.
Rates and conditions depend on each structure. Specialist tax and legal advice should be taken before any decision.
A time zone that overlaps Africa, the Gulf and India.
Connected
Modern air and sea connectivity.
Stable
Ranked second in Africa in the 2024 Ibrahim Index of African Governance.
Residency for investors and professionals
Occupation Permits for investors, professionals and the self-employedResidence permits linked to approved property schemesWork and Live framework, reformed in Budget 2026/27Golden Visa pathway, introduced in Budget 2026/27
Eligibility thresholds have tightened. Current requirements should be confirmed with the Economic Development Board before any application.
Sources: Financial Services Commission Mauritius; Mauritius Revenue Authority; Economic Development Board; Deloitte Tax Highlights 2026; Sovereign Group and Rosemont Budget 2026/27 briefings; FATF; WIPO. General information, not legal, tax or investment advice. Information as at October 2026.
A boutique firm built on three decades in banking.
A boutique consulting firm across the Asia–Mauritius–Africa corridor, led by our founder.
A message from the founder
I have spent three decades on the banker’s side of the table, in corporate, international and central banking, across Africa, India and the Middle East. Most of that time went into syndications and trade finance: arranging the financing that moves goods and capital across borders.
In that work I kept seeing the same pattern. Good businesses and sound projects struggled to reach the right banks, DFIs and private credit providers, and capital struggled to find opportunities it could trust. What was missing was rarely money or ambition. It was structure, preparation and a steady guide through the process.
That is why I founded Nakhoda. The word comes from the Persian nākhudā, the master of a ship: the person who knows the waters, holds the course and has the answers for the voyage. It is the role I want to play for my clients.
My vision is simple. Africa’s potential is large, and it needs capital, banking relationships and sound structures to be realised. With Mauritius as our hub, Nakhoda connects that capital to the trade and projects that support the continent’s development, independently and with the discipline of a banker.
If you are looking to finance, structure or buy something across the corridor, tell me what you are trying to achieve. I will tell you plainly whether and how we can help.
Kris JhurryFounder, Nakhoda
Our name
Nakhoda
From the Persian nākhudā, the master of a ship. Traders and sailors across the Indian Ocean have used the word for centuries, from the Gulf and India to East Africa and the islands, for the person who knows the waters, holds the course and answers for the voyage.
Our mark is a compass star with a brass north point: the one who guides.
Our vision
To help unlock Africa's potential by making capital easier to reach and cross-border trade safer to do.
Africa's potential
Africa has the youngest and fastest-growing population of any continent, deep natural resources and a continental free trade area, the AfCFTA, that is opening its markets to one another. Realising that potential takes financing, guarantees and trade structures that many businesses and projects still find hard to reach.
A young, growing market
A rising working-age population is creating demand for jobs, housing, energy and services.
Resources and projects
Agriculture, minerals, energy and infrastructure projects all need long-term finance.
Opening trade
The AfCFTA, SADC and COMESA are widening access between African markets, and CECPA links Mauritius with India.
How we help
Connecting capital to African businesses and projects
Introducing corporates and projects to DFIs, banks and private credit providers.
Making businesses bankable
Help preparing the documentation banks and lenders ask for, in English and French.
Supporting trade across the corridor
Buyer–supplier matchmaking, logistics, customs and payment structuring between Asia, Mauritius and Africa.
Using Mauritius as a gateway
Global Business Company structures and treaty-based routing into Africa.
Our values
How we work with clients, partners and counterparties.
We are a small firm, and our reputation is the most valuable thing we have.
Our principles
01
Candour
We are clear about our role, honest early, and plain in our language.
02
Prudence
We vet every counterparty, follow AML and KYC everywhere, and decline what does not meet our standards.
03
Partnership
We respect licensed partners, treat every party with courtesy, and build for the long term, in Africa and beyond.
Leadership
The founder who leads Nakhoda, and the senior voices who share their experience of markets, finance and world affairs.
Founder
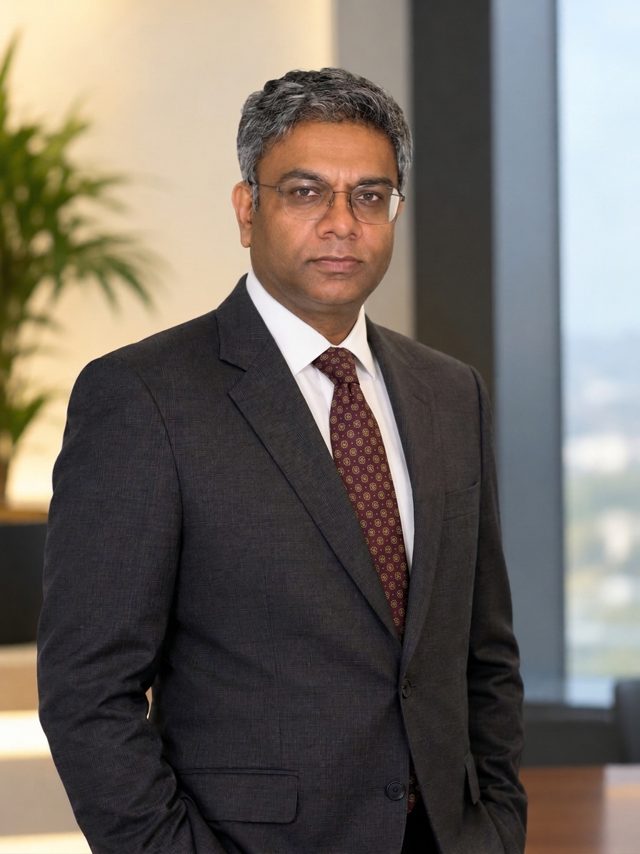
Balkrishna (Kris) Jhurry
Founder
Kris Jhurry has spent three decades on the banker's side of the table, in corporate and international banking and in central banking across Africa, India and the Middle East. Most of that time went into syndications and trade finance: arranging the financing that moves goods and capital across borders.
Today he brings that experience, and a network of banks, DFIs, private credit and institutional guarantors, to businesses that need a steady, trusted guide through complex cross-border transactions.
Nakhoda is a small firm by design, so the person you meet is the person doing the work. Our founder brings three decades in banking and a network across the corridor to every introduction and mandate.
Global Advisory Network
We keep in regular conversation with respected figures from business, policy and academia, drawing on their experience of markets, finance and world affairs. As our reach widens, regional panels keep us close to senior business voices in our main markets.
Advisors will be announced here
Our network is growing, and we will introduce each advisor here as they join.
Views on trade finance, Mauritius and the corridor.
Notes for clients and partners on what is changing and what to check before committing.
USD 375,000Minimum purchase for a residence permit in an eligible scheme
5%Registration duty for EDB schemes after the 2026 reversal
Rs 6 millionWhere Ground + 2 apartments start
6 stepsFrom settling your purpose to the permit application
Mauritius is one of very few places where a foreigner can own a freehold home and, in the same transaction, earn the right to live there. That is a real draw, and it is also why the island attracts so much half-true advice. Most of what goes wrong for buyers goes wrong in the gap between “you can buy” and “you can buy this, this way.”
Myth 1
“Foreigners can’t buy property in Mauritius.”
They can, but not on the open market. Non-citizens buy inside government-approved schemes administered through the Economic Development Board (EDB). The scheme you choose decides what you can own, what it costs and, importantly, whether a residence permit comes with it.
Scheme
What it is
Residence permit?
Property Development Scheme (PDS)
Approved residential developments. The main route for new purchases today.
Yes from USD 375,000. Valid while you own; can cover family under 24.
Smart City Scheme
Large mixed-use districts combining homes, offices and amenities.
Yes same USD 375,000 threshold.
IRS / RES (legacy)
Older resort and real-estate schemes. Still relevant mainly for existing stock and resales.
Yes same threshold.
Invest Hotel Scheme
Hotel-linked units, often with a leaseback arrangement.
Possible at USD 375,000, but tied to the leaseback conditions.
Ground + 2 apartments
Apartments in buildings of two or more floors, from Rs 6 million.
No residency from ownership alone; only at USD 375,000+.
A route outside the schemes (a single home, at a minimum of USD 500,000, for people who already hold a permit) has been introduced, restricted and debated over the past few years, and published sources currently disagree about its status. If someone offers you a property outside a scheme, make the notary and your adviser confirm in writing that the purchase is lawful before you pay anything.
Myth 2
“Buy a villa and residency comes automatically.”
Only up to a point. A purchase of at least USD 375,000 in an eligible scheme makes you eligible for a residence permit that lasts for as long as you own the property. It is a genuinely good deal: no minimum-stay requirement and the right to work, without a separate occupation permit. But it is an application, made to the EDB after the deed is registered, not a feature of the house.
Three distinctions catch people out. First, a permit holder is still a non-citizen, so later purchases must also fit an approved category. Second, owning a Ground + 2 apartment at Rs 6 million does not by itself buy you the right to settle. Third, the new Golden Visa is built around productive investment: USD 1 million into an economic activity, with the value of a home bought under an EDB scheme expressly excluded. A USD 1 million villa is not a Golden Visa.
Myth 3
“Duties on foreign purchases doubled this year.”
You will still find this in guides published earlier in 2026, and it was indeed the plan. The Finance Act 2025 set registration duty and the seller’s land transfer tax to rise from 5% to 10% on 1 July 2026 for non-citizens buying under EDB schemes. The Finance Act 2026 (Act No. 14 of 2026, presidential assent on 12 August) reversed that. For EDB-approved developments, registration duty stays at 5%, and the seller’s land transfer tax is also 5%.
Two caveats. Deeds registered between 1 July and the new law taking effect may have been charged at the higher rate, and the legislation does not clearly provide for automatic reimbursement, so anyone in that window should ask their notary. And a different, narrower charge now exists: a 10% additional duty, payable by the seller, on a specific type of Ground + 2 sale to non-citizens on state land or Pas Géométriques land. Buyers do not pay it directly, but sellers may price it in. It generally does not apply where a qualifying agreement was signed before a notary before 19 June 2026.
Budget beyond duty as well: notary fees on a sliding scale, VAT on professional services, and the syndic (management) fees that common areas in PDS and Smart City developments carry year after year. Rental income is taxable, so model your yield after tax rather than before it.
The journey
How a purchase actually runs
Settle your purpose.Lifestyle home, residency, or yield? The answer narrows the schemes and the price bracket immediately.
Choose an approved development.Confirm the project holds the relevant EDB scheme approval before falling in love with a show villa.
Appoint a registered agent and a notary.The notary is central in Mauritius: they verify the title, the legal basis for your acquisition and the correct duty.
Reserve and run due diligence.A signed reservation or promise of sale before a notary, with conditions. Check title, permits, developer track record and, off-plan, the exact type of contract.
Sign and register the deed.Ownership is formally recorded with the Registrar-General. Duty is paid at registration.
Apply for the residence permit.If your purchase qualifies, the application goes to the EDB with a certificate from your notary, your passport and a health declaration.
Watch for
Where buyers get caught
“Private beach.”
The government is actively challenging beach-access restrictions, and the Ministry of Housing and Land has begun acting against fences, ropes and other structures on stretches marketed as private. A plot can be privately owned up to a boundary without the sand in front of it being private. For coastal property, title checks should cover cadastral boundaries, the High Water Mark, the Building Line, rights of way and the status of any structure the seller built.
Pas Géométriques titles.
The ministry has announced that 364 sites on this strip, sold between 2014 and 2016, will be treated as illegally transferred. Not every title is in question, but the origin of the title and each successive transfer now deserve real scrutiny.
Off-plan enthusiasm.
A glossy brochure is not a contract. Whether you hold a proper preliminary reservation contract, rather than a private reservation or letter of intent, can decide both your protections and your tax position.
Stale advice.
Duty rates, thresholds and eligible routes have shifted repeatedly in recent Finance Acts. Check the date on any guide, ours included, and check it against the current Act.
Sources and notes
Sources consulted (October 2026): Finance Act 2026, Act No. 14 of 2026 (Mauritius Assembly); Non-Citizens (Property Restriction) Act (Attorney General’s Office); Economic Development Board residence-by-property pages (residency.mu); Expat.com, “Mauritius tightens foreign and coastal property rules” (18 August 2026); Ministry of Housing and Land statements on public beach access. Thresholds and rules are subject to change and to the facts of each case.
General information only, not transaction, legal or tax advice.
41%of Mauritian imports come from just three partners: China, the UAE and India
25%of exports go to South Africa, Madagascar and Kenya alone, three African markets
46tax treaties anchor the island’s role as a base for Africa- and Asia-facing capital
Trade shares: US Commercial Service (Feb 2026). Treaty count: Chambers, Investment Funds 2026.
Mauritius has signed its way onto several trade maps at once: two African regional blocs, a continental free-trade agreement, and bilateral deals with India, China and the UAE. The question is no longer whether the corridor exists on paper, but where it actually carries traffic.
The map
Six agreements, five different jobs
There is no single Mauritian trade deal, only a set of tools. Each connects the island to different partners, and each has a catch that decides whether it is useful to you.
Agreement
Connects Mauritius to
What it gives
The catch
India CECPA in force 2021
India
Preferential access across 615 products, plus services commitments.
A narrow goods list. Expansion talks were due on 7 October; no outcome published at the time of writing.
China FTA in force 1 Jan 2021
China
Goods, services and investment: thousands of duty-free tariff lines and more than 100 service sectors opened.
Mauritius is still phasing down its own duties, and preference depends on proof of origin.
UAE CEPA in force 1 Apr 2025
United Arab Emirates
Free-trade area covering goods, services and investment.
Tariff-rate quotas on some goods and a few excluded lines. Activation, not signature, is the test.
SADC and COMESA
16 SADC states; COMESA members incl. Egypt, Kenya, Madagascar, Zambia
Duty-free trade in SADC in principle; duty- and quota-free trade in COMESA.
Angola, the DRC and the Comoros are not yet in the SADC FTA. Sugar into the SACU market is quota-limited.
AfCFTA
23 partners listed for preferential trade, including South Africa, Kenya and Nigeria
Imports from members enter Mauritius duty-free; Mauritian exports get preferential terms where partners have ratified.
Product-specific rules. Rules for key exports such as sugar, tuna and clothing were still unfinished in the last published analysis.
Layer one: goods
The paperwork is the product
A tariff cut only reaches your goods if they qualify as Mauritian in origin. Under the AfCFTA, for example, simple operations such as washing, basic pressing, painting or packaging do not confer origin on their own. Certificates are issued by the Mauritius Revenue Authority’s Customs Department through TradeNet, and applicants typically need costing evidence and proof of the materials used.
That changes how to read the “gateway” story. The port, the logistics and the legal system are real advantages, but a re-labelling hub does not carry a preference with it. Where Mauritius shines is where genuine transformation happens on the island or inside the region: processed food, apparel, light manufacturing.
The US is the cautionary example. AGOA preferences lapsed for about four months from 30 September 2025 and have reportedly been extended to the end of 2028, subject to annual review. The US takes roughly 11% of goods exports, and about USD 70 million of manufactured exports depend on the preference. One market on one legislative clock is the exposure that Africa and Asia agreements help to diversify.
Layer two: capital
Where the corridor is strongest
Mauritius has about 46 tax treaties and 29 investment protection agreements. The Financial Services Commission listed 949 global funds in June 2025, and industry bodies put the number of Africa-focused funds domiciled on the island at nearly 500 (a figure from a sponsored regional report, so treat it as indicative). Treaties with several African states, including Kenya, Rwanda, Uganda, Zambia, Mozambique and Senegal, help soften withholding taxes on flows into the continent.
The model has matured. The old India route lost its capital-gains advantage in stages through 2019, and a 2024 protocol adds a Principal Purpose Test; Mauritius approved ratification in July 2026. What is left is not a loophole but a platform: funds, special purpose vehicles and holding companies that can show real substance. For funds, partial income exemptions of 80%, and 95% on interest, depend on genuine activity in Mauritius, qualified people and proportionate local spending.
The reputational work has largely been done: Mauritius left the FATF grey list in October 2021 and the EU’s high-risk list in 2022. And the island is now used from more directions. The China agreement opened financial services to Chinese participation, and the UAE agreement carries its own financial-services commitments.
Putting it to work
What to do with the map
If you are…
The opportunity
Your first move
An Asian buyer or sourcing team
Serve African markets from a base with preferential access, finance and a stable legal system.
Trace the origin rule for your product before choosing a location, and ask what transformation really happens on the island.
An African supplier
Reach India, China and the UAE through Mauritian partners.
Remember that preferences attach to Mauritian-origin goods. A processing step must be commercially real; a relabel will not carry the preference.
A Mauritian SME or investor
Supply the services and structures both sides need: logistics, legal and professional services.
Pick one corridor and one offer, and put the licences and origin documentation in place before marketing it.
A fund manager or investor
Africa- or Asia-facing vehicles built on treaty access.
Budget for substance (resident directors, local spend) and test the treaty position for each target country, including India’s new test.
Watch for
What to watch
Activation and the India talks.
The head of the Economic Development Board has said the aim for the next one to two years is to move from agreement to activation, which is the right test. CECPA expansion talks (more products, easier standards, recognition of professional qualifications) were scheduled for 7 October.
Origin rules, frictions and scale.
Strict origin rules and the customs and standards frictions outside tariffs are where most corridor deals quietly stall. And with an economy of around USD 15 billion, Mauritius’s value lies in through-traffic and in what is built on the island, not in domestic demand.
Sources and notes
Sources (October 2026): Bowmans (2021); US Commercial Service (Feb 2026); Mauritius International Trade Division; Mauritius Revenue Authority notices; MCCI; Chambers, Investment Funds 2026; Rio Times (Sept 2026); Gulf Business (June 2026, sponsored); Trade Economics (2023); Newsbytes (Sept 2026). Figures and rules change often; verify against official sources before any decision.
General information only, not transaction, legal or tax advice.
2Mauritius-resident directors required at all times for a GBC
46tax treaties, with Africa-facing and Asia-facing partners
6–8weeks to set up with complete documentation; bank account typically 2–4 weeks
Treaty count: Chambers, Investment Funds 2026. Timings are typical, from practitioner guidance, and depend on the complexity of the structure.
Every Africa-bound structure now faces the same test: a bank’s compliance team, reading the file from the outside. The structures that pass are not the cleverest. They are the ones whose answers are simple, documented and true. That is the strongest case for a Mauritius Global Business Company (GBC): the island’s regime has been rebuilt around exactly those questions.
The bank’s-eye view
Five questions, and how a GBC answers them
Put yourself in the compliance officer’s chair. Whatever the deal, the file has to answer the same five questions. Here is how a properly run Mauritian GBC fares.
The question
What the bank wants to see
How a Mauritius GBC answers
1. Who is behind it?
Every ownership layer, the ultimate beneficial owners and the source of funds.
A licensed management company runs KYC on the structure. Written beneficial-ownership declarations, a resident authorised officer and updates within 14 days of any change.
2. Where is it really run?
People, premises and decisions in the stated jurisdiction.
At least two resident directors at all times, board meetings in Mauritius, local records and audited accounts, and a principal local bank account.
3. Why Mauritius?
A commercial rationale beyond tax.
A treaty and investment-protection network of about 46 tax treaties and 29 investment agreements, a regulated fund and holding regime, and trade agreements that link Africa and Asia.
4. Is the regime credible?
A supervisor that enforces, and no reputational baggage.
FSC-regulated. Left the FATF grey list in October 2021 and the EU high-risk list in 2022. Graded AML penalties in force since November 2025.
5. Will it survive new rules?
Resilience to global minimum tax and transparency trends.
Already aligned with OECD standards. A domestic minimum top-up tax applies only to groups with EUR 750 million or more in revenue; investment funds are excluded.
Substance in practice
The rule changed; the direction did not
Banks used to ask whether a structure had substance. They now ask to see it. In June 2026 the Financial Services Commission updated its guidelines for management companies so that every GBC bank account must include at least one authorised signatory who is an officer of the licensed management company. The rule took effect on 19 June 2026, with a three-month transition for existing structures that should now have run its course. Listed companies and certain multinationals may be exempt.
For a well-run GBC this is a feature, not a burden: the people who see the paperwork also see the payments. It gives the bank what it increasingly wants, which is evidence that local directors and administrators have real visibility over transactions and decisions. Funds and holding companies that want the 80% partial income exemption carry a further test: core income-generating activities in Mauritius, an adequate number of qualified people, and proportionate local spending.
Treaty access, honestly
What the network does, and does not, deliver
The headline numbers are attractive. A GBC is taxed at 15%, and an 80% exemption on specified foreign-source income, including foreign dividends and interest, brings the effective rate on those items to about 3%. Mauritius levies no withholding tax on dividends it pays, nor on interest a GBC pays to non-residents out of foreign income. A 2023 count put the treaties with African states at 17, with more in the pipeline.
The honest version has three caveats. First, the exemption and an actual foreign tax credit cannot both be claimed on the same income. Second, relief at the African end depends on each source country’s own treaty terms and anti-abuse rules, and those are tightening: the revised South Africa treaty added anti-abuse measures, and the India protocol now adds a Principal Purpose Test. Third, no treaty rewards a structure with no commercial purpose. The advantage goes to those who can show why the money is routed this way.
Getting started
A readiness checklist
Write down the commercial rationale.One page: what the structure holds, where the money comes from and goes, and why Mauritius.
Choose a licensed management company.Every GBC needs one. It files the licence application and acts as your link to the FSC.
Appoint resident directors with real authority.Two or more, who take part in decisions and hold board meetings in Mauritius.
Build the substance file.Board calendar, premises, people, local spend and records, kept as you go rather than reconstructed later.
Prepare the bank pack.Group chart, UBO documents, source of funds and the business plan, clean and complete.
Keep it current.Notify the FSC of director changes within seven days, update beneficial-ownership records within 14 days, and file audited accounts within six months.
Sources and notes
Sources (October 2026): PwC Tax Summaries, Mauritius (reviewed June 2026); KPMG, Mauritius Finance Bill 2025; IQEQ on the QDMTT (October 2025); Chambers, Investment Funds 2026; Rosemont on the FSC bank-signatory guidelines (June 2026); Intercontinental Trust compliance update 2025-26; Kalexius on beneficial ownership (2026); Bolder Group on Mauritius’s African treaties (2023); Rio Times (September 2026); GoGlobal GBC guide. The effective rate quoted is arithmetic from the 15% rate and 80% exemption and depends on meeting all conditions. General information, not tax or legal advice.
General information only, not transaction, legal or tax advice.
10M–50Bface values quoted in lease offers, in USD or EUR, as described in practitioner warnings
1 yr + 1 daythe tenor these offers typically specify
Mostgenuine SBLCs expire undrawn: a backup, not an asset that earns a return
Sources: ICC Academy SBLC guide; IIBLP on prime bank schemes (undated); FBI alert I-031819-PSA (March 2019).
A standby letter of credit (SBLC) is an everyday trade-finance tool. An offer to lease one to you, or to “monetise” one for funding, is a different matter, and regulators have been warning about those pitches for years. You do not need to be a trade-finance specialist to tell the two apart. You need to ask five questions, in the right order, before you spend any money or lend your name to anything.
The instrument
What a genuine SBLC looks like
An SBLC is an independent undertaking, usually by a bank, to pay the beneficiary if the applicant fails to perform or pay. The applicant asks its own bank to issue it, and the bank decides on the applicant’s credit, size and collateral. Only the named beneficiary can draw on it. The ICC calls the draw a “payment of last resort”, and most SBLCs expire undrawn because the underlying contract is performed.
It is typically governed by published rules, with the ICC’s ISP98 designed specifically for SBLCs, and its terms mirror a real contract: who is the applicant, who is the beneficiary, what amount, what expiry, and what documents are needed to draw. The issuing bank charges an issuance fee for the life of the instrument. Nothing in that picture involves a third party leasing the instrument to strangers.
A genuine SBLC
A typical lease or monetisation pitch
Purpose
Backs a named contract; a fallback that is usually never drawn.
Presented as an asset to be leased, sold or used as collateral to unlock funding.
Who asks for it
The applicant, through its own bank, against its credit or collateral.
A “direct provider” or broker approaches an unrelated recipient, often by unsolicited email.
Size and term
Sized to the underlying contract.
Face values quoted from USD or EUR 10 million up to 50 billion, usually for one year and one day.
Fees
An issuance fee charged by the issuing bank.
Lease and sale fees quoted as percentages (often written like “6+2%”), with advance fees demanded before any funding.
Delivery
Issued by the bank through its own channels.
“SWIFT-to-SWIFT” claims, MT103 payments, hard copies by bonded courier.
The five checks
Ask these before you engage
Take them in order. A single failure is a reason to pause. Several failures are a reason to walk away.
Check
What to ask
Walk away if…
1. Purpose
Who is the applicant, who is the beneficiary, and what contract does the instrument back?
Nobody can name an underlying contract, or the instrument is to be “leased”, “monetised” or used as collateral for a loan.
2. Issuer
Is the issuing bank licensed, and does it confirm the instrument when you contact it using details you found yourself?
You are discouraged from contacting the bank, or the only contact details are the ones printed on the documents.
3. Money
Who is paid, how much, and when? What exactly do you receive in return?
Any fee is due before the issuing bank has confirmed anything, or funds must move through escrow, “blocking” or a third-party account.
4. Proof
What are you actually being shown: a verifiable bank-to-bank message, or a copy, screenshot or forwarded printout?
“Proof of funds” arrives through intermediaries. Counterfeit SWIFT messages (MT 799, MT 760) have been used in documented frauds.
5. Chain
How many parties sit between you and the bank, and what does each one earn?
Unsolicited broker outreach, early secrecy or NDAs, urgency, requests to introduce others, or elaborate excuses when promised funds fail to arrive.
The FBI’s 2019 alert on fictitious SBLCs lists the same pattern: returns out of proportion to the risk, imitations of real instruments, “non-recourse” or “forgivable” loans, advance fees, transfers through foreign banks, improper references to real institutions, heavy secrecy, and the word “monetize”. It adds that the technical nature of SWIFT messages and SBLC transactions is what lets fraudsters exploit a victim’s limited knowledge. The defining feature, it says, is a promise of a high-return or risk-free loan from a source that is obscure or cannot be verified.
A Mauritius note
Verify the people and the bank, separately
Offers can cite offshore or Mauritian entities, and a name on a letterhead can feel reassuring. It should not be taken as proof of anything. Banks and non-bank financial firms are supervised by different bodies, so check each claim with the right one. The Bank of Mauritius publishes the list of licensed financial institutions, and in July 2020 it cautioned that fake guarantees, including performance and advance payment guarantees appearing to be issued by licensed banks, were in circulation. The Financial Services Commission keeps a public Register of Licensees and publishes investor alerts and notices when an entity’s licence status changes. Its mail address for queries is [email protected].
Sources and notes
Sources (October 2026): FBI Internet Crime Complaint Center, alert I-031819-PSA (March 2019); ICC Academy, Comprehensive Guide to Standby Letters of Credit; IIBLP, “Beware of prime bank investment scams” (undated); ICC Financial Investigation Bureau on a fake standby letter of credit (February 2008); Bank of Mauritius public notice on fake guarantees (7 July 2020); Financial Services Commission, Mauritius, licensee notices (August 2026); Trade Finance Global on SWIFT MT 760. General information, not legal or financial advice.
General information only, not transaction, legal or tax advice.
6 monthsmaximum age of a certificate of incorporation or registry extract at one Mauritian bank
3 monthsmaximum age of proof of address and bank reference letters at the same bank
18 monthscompany age after which banks typically ask for financial statements or an annual return; younger companies show bank statements
Examples from published checklists of MCB and Bank One (Mauritius) and the Mauritius IFC guide. Every bank sets its own limits; always use the checklist of the bank you are applying to.
Most delayed applications are not refused. They simply keep coming back: one more document, a clearer chart, a fresher letter. Each return costs a full review cycle, and the causes repeat from file to file. That is good news, because a gap that repeats can be closed before the application is ever submitted.
Where it stalls
Four gaps, and the early fix for each
Banks must understand a company’s structure, its shareholders and its beneficial owners, partly to meet tax-reporting duties such as FATCA and CRS. When the file leaves any of that unclear, the reviewer has no choice but to ask. Each gap below is a question a prepared applicant can answer in advance.
The gap
What the bank is trying to confirm
The early fix
1. Ownership and UBO
Who ultimately owns and controls the entity, traced through every layer to named individuals.
Draw the structure chart first, with percentage holdings down to individuals. Make the registers, the beneficial-owner declaration and the chart say the same thing. Add full documents for any corporate shareholder or trust in the chain.
2. Source of funds and wealth
Where the money for this account comes from, and how the owners came to hold their wealth.
Treat them as two questions. Funds: documents showing the origin of this money. Wealth: how the owner’s assets were built, such as financial statements, loan agreements, evidence of gifts or inheritance, or an accountant’s or solicitor’s letter. Keep the evidence recent.
3. Form and certification
That every document is genuine, current and certified by an acceptable person.
Read the bank’s checklist for who may certify, what the certifier must show, and how old each document may be. Certify once, correctly, and keep a dated tracker.
4. Business rationale
What the entity does, who it deals with, and what flows to expect.
Write a short, signed business plan covering activities, counterparties, sources and uses of funds, and expected inflows and outflows. Make every figure traceable to a document in the pack.
The small things
Why the paperwork itself is a delay
Two of the four gaps are about form, not substance, and they are the cheapest to fix. Published bank checklists show how specific the rules are. One Mauritian bank requires registers and resolutions to be signed by a licensed referrer or introducer acting as a director, company secretary, asset manager or fund administrator, while directorship and shareholding confirmations may come from a notary or attorney. Another accepts management companies, consulates, notaries, lawyers, solicitors (with apostille) and other regulated professionals, but requires the certifier’s full name, address, occupation and registration number to be clearly visible.
The pattern is consistent: the right person, in the right form, with the right date. Onboarding guidance from one payments provider adds that minor variations in company names, outdated director listings and incomplete beneficial-owner disclosure all slow a review down. Checklists also separate items that block an application from those that do not, so it pays to know which is which.
The readiness pack
Six steps before you submit
Start from the bank’s own checklist.Banks publish them, and they differ on validity periods, accepted certifiers and which items are mandatory.
Draw the ownership chart first.Percentages, names and jurisdictions, traced to individuals. Everything else is checked against it.
Write the business plan next.Activities, counterparties, expected flows and where the money comes from, signed and dated.
Gather evidence for funds and wealth.Match each statement in the plan to a document, and check that the dates are recent.
Certify once, in the right form.Confirm who may certify, what they must write, and whether translations or apostilles are needed.
Read it once as a stranger would.Names, dates, addresses and signatures should match across every document. Then submit it complete.
What preparation cannot do. Not every delay is the client’s file. Banks also weigh their own risk appetite, and industry commentary notes that complex clients cost more to onboard, so a bank can decline a client that does not fit. Mauritius IFC guidance says plainly that banks reserve the right to reject an application, and bank checklists add that further documents may be requested on a risk basis. A strong pack removes avoidable delay. It does not remove the bank’s discretion.
Sources and notes
Sources (October 2026): MCB checklist for foreign companies (account opening); Bank One list of documents for foreign GBC accounts (2022); Mauritius IFC, company bank accounts; Airwallex on KYC document certification; Paperjam on corporate bank accounts in Luxembourg (19 October 2026); First AML on source of wealth and source of funds. Requirements vary by bank and change over time; confirm with the bank. General information, not legal or compliance advice.
General information only, not transaction, legal or tax advice.
74–92bnUSD: the African trade finance gap in 2024, about 5.4% of merchandise trade (AfDB)
37%of trade finance applications rejected by banks in 2020–24; SME approval averaged 63%
23%of African trade intermediated by commercial banks in 2020–24, down from 40% before the pandemic
Sources: AfDB, Trade Finance Supply in Africa: Post-COVID Trends and Emerging Opportunities (2026), as reported by GTR and BusinessDay.
Africa’s trade finance gap is usually reported as a problem. It is also a measure of how much trade is waiting for the right kind of finance. Tens of billions of dollars of demand go unmet each year, even as African trade keeps growing.
The gap
Why trade finance goes unmet
The African Development Bank’s 2026 trade finance report puts unmet demand at USD 74–92 billion in 2024. Commercial banks intermediated just 23% of African trade in 2020–24, down from 40% before the pandemic, and they rejected 37% of trade finance applications. SMEs fared worst, with approval averaging 63%.
The AfDB and other surveys point to a consistent set of causes. Foreign-exchange liquidity is now the main obstacle, cited by 36% of African banks, up from 18% in 2015–19. Thirty per cent cite obligor limits with correspondent banks, and 27% each cite shortages of risk capital and regulatory restrictions. Compliance costs weigh most heavily on small transactions and small banks, and only 28% of surveyed banks use digital trade finance tools.
The potential
A gap of appetite, not of trade
The numbers argue that trade is not the weak link. Africa’s merchandise trade grew 6.1% to about USD 1.5 trillion, and intra-African trade rose an estimated 5.5% to USD 213.8 billion in 2025, according to Afreximbank’s 2026 report. Before any new shock, the AfDB’s own baseline had the gap continuing to narrow toward USD 65 billion.
The 2026 risks cut the other way. The AfDB’s moderate scenario, built on sustained high oil prices after the Middle East conflict that began in February, takes the gap to USD 86.6 billion by 2027, about 18% above the 2024 level, and the upper range reaches USD 102.6 billion. Afreximbank, for its part, aims to double intra-African trade finance by 2026.
Why Mauritius
A small economy with outsized connections
Mauritius has an economy of about USD 15 billion, so it is not a source of balance sheet on the scale of the gap. Its relevance lies elsewhere: a banking sector with African networks, a regulated financial centre with about 46 tax treaties, and a fund industry that has long served Africa- and Asia-focused capital.
Mauritian banks are already moving. MCB announced a USD 1 billion trade finance initiative over four years in May 2026, and in August signed a confirming-bank agreement with the AfDB. The island has also rebuilt its regulatory standing, leaving the FATF grey list in October 2021 and the EU high-risk list in 2022, which matters in a market where correspondent banks choose their partners carefully.
How much of the opportunity Mauritius realises will depend on capacity, partnerships and trust, and on how quickly the 2026 shocks ease. The direction of travel, though, is clear.
Sources and notes
Sources (October 2026): AfDB trade finance report 2026 as reported by GTR and BusinessDay (29 May 2026); ADB Briefs No. 378 (December 2025); Afreximbank African Trade Report 2026 (via Zawya and The Reporter, June 2026); MCB announcement (Ecofin, 29 May 2026) and AfDB confirming-bank agreement (August 2026); Chambers, Investment Funds 2026. Figures differ across sources and years; verify before relying on them. General information, not financial advice.
General information only, not transaction, legal or tax advice.
Nakhoda is a consulting firm. It does not manage funds, take deposits or offer investments, and nothing on this page is investment, legal or tax advice. Any regulated activity is carried out by licensed partners.
Where you can meet us.
The conferences and summits our team will attend. If you will be there too, get in touch and we will arrange a time to meet.
Upcoming
6–9December2026
Attending · Mauritius
U.S.–Africa Business Summit
The Corporate Council on Africa’s flagship gathering of business leaders, investors and governments, hosted this year with the Government of Mauritius. It brings together the people shaping trade and investment between the United States and Africa.
Nakhoda will be attending. We would be glad to meet clients, banks, investors and partners during the summit.
More events will be added here as they are confirmed.
Privacy and cookies
How Nakhoda handles the information you give us through this site.
Who we are
Nakhoda Consulting Ltd (BRN C26240671), 32 Rue Montpellier, Résidences Trianon, Quatre Bornes, Mauritius, decides how your information is used. You can reach us at [email protected].
What we collect
Only what you type into the contact form: your name, organisation, the type of enquiry, your email address and the areas you need help with. Our hosting provider also processes technical data such as your IP address to deliver the site and keep it secure.
Why we use it
To reply to your enquiry and, if we work together, to carry out that work. We do not sell your information and we do not use it for advertising.
Who else handles it
We use Cloudflare to host the site and protect the contact form from spam, and Resend to deliver the form to our inbox. These providers may process data outside Mauritius under their own safeguards.
How long we keep it
For as long as we need it to handle your enquiry and any resulting engagement, and for any period the law requires. After that we delete it.
Your rights
Under the Mauritius Data Protection Act 2017 you can ask to see your information, correct it, have it deleted, object to how it is used, or withdraw your consent. Email us and we will respond. You can also complain to the Data Protection Office of Mauritius.
Cookies
This site does not use advertising or analytics cookies. The spam check on the contact form (Cloudflare Turnstile) may store a small token that is strictly necessary to protect the form, and we store a note in your browser that you have seen the cookie notice. Nothing else is stored, and the fonts are served from this site.
Last updated October 2026.
This site uses only the cookies and storage it needs to work, including spam protection on the contact form. We do not use advertising or analytics cookies. Privacy and cookies